Why you find out what a flip made at the closing table
If your deal pipeline is one spreadsheet and every rehab budget is another, you learn what a flip made at closing. How one record per property changes that.
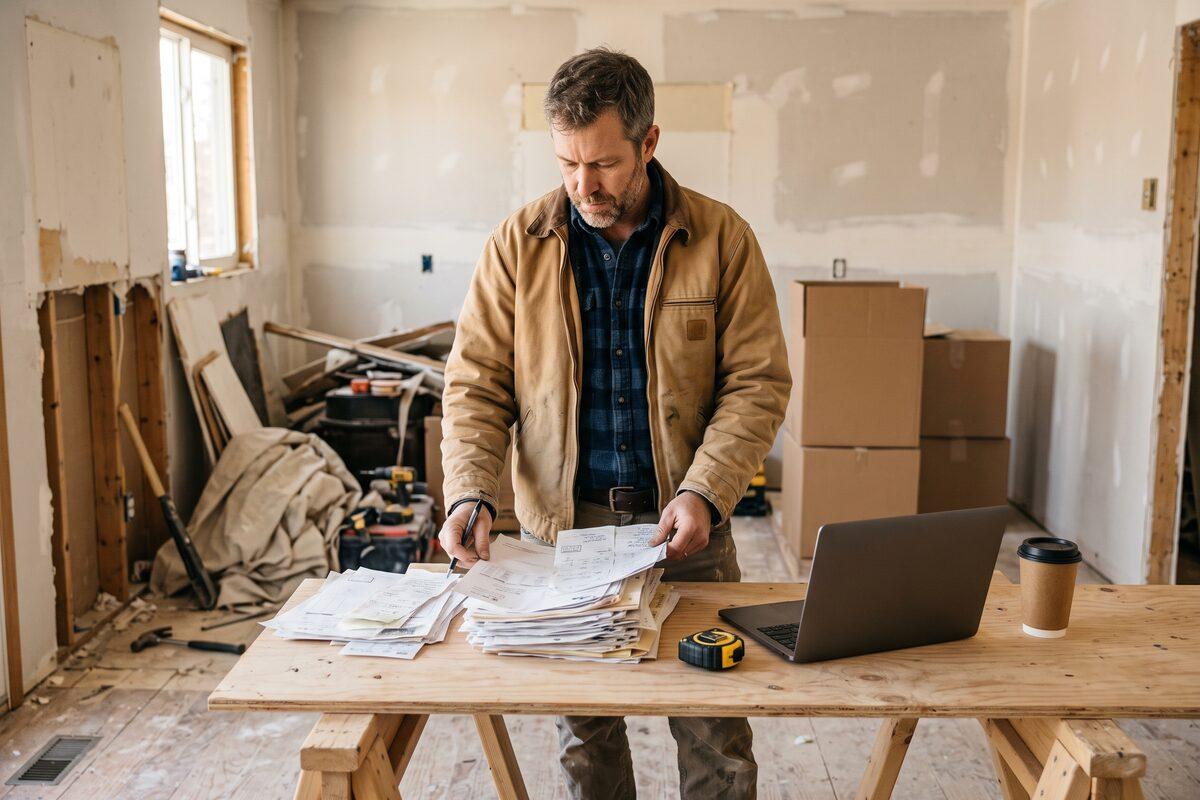
The closing statement is where you learn what the flip made
You bought the house in March. The rehab budget was a workbook you built the week you wrote the offer: line items for roof, kitchen, paint, and flooring. The crew started in April. Then the plumber found the cast iron, the cabinets came in over the allowance, and three change orders went by text message.
Now it is July, the house is under contract, and you are sitting with the closing statement trying to work out whether this one made money. Contractor invoices are in email. Draw requests are in the lender portal. Receipts are in a photo roll. The budget workbook stopped being updated in May because nobody had time.
Meanwhile the next deal is in a different spreadsheet. Wholesaler leads, direct mail responses, and agent referrals go into a sheet with a column for offer price and a column for status. Which ones got a follow-up call last week depends on who remembers.
This post is for the owner of a small real estate investment company, someone doing a handful of flips a year while holding a few rentals, with a partner or two and a bookkeeper who comes in monthly. If you have a project manager updating your numbers every day, this is not for you.
What changes when every property carries its own numbers
The outcome: you know where a rehab stands against its budget while the crew is still in the house, and you know what the deal made before you sign the closing documents, not after.
Kairos Software helps small real estate investors see the real margin on every deal by building a single record per property that holds the lead, the offer, the rehab budget, and every cost charged against it, from the day you first look at the house to the day you sell it.
Here is how that works in practice.
- One record from lead to sale. A property is entered once, when it comes in as a lead. The offer, the purchase, the rehab, the listing, and the sale all attach to it.
- The budget and the actuals sit together. Each rehab line item has a budgeted amount and a running total spent against it. An invoice is logged to its line item the day it arrives, from a phone, and the variance updates on its own.
- Change orders are recorded, not texted. When the plumber finds the cast iron, the added scope goes in as a change order against that line, with the amount and who approved it. The budget total moves and you can see why.
- The pipeline shows what needs doing. Each lead has a stage and a next action with a date. The list you open in the morning is the deals waiting on you.
Your accounting system stays. The bookkeeper still closes the month in QuickBooks, and the per-property totals that go to the books come from the same record instead of being rebuilt from receipts. How that handoff works is covered in how custom software works with QuickBooks.
Why one record gets you the margin before closing
The margin on a flip is the sale price less the purchase price, the rehab cost, and the holding and selling costs. Three of those four numbers are known early. The one that moves is rehab cost, and it moves in small increments across dozens of invoices and change orders over three or four months. A workbook can hold that number only if someone updates it every time an invoice arrives, and in a small shop that someone is also the person negotiating the next deal.
When each cost is logged against the property at the moment it is incurred, the running total is a byproduct of paying the bill, not a separate chore. The question of whether a project is over budget then has an answer every day of the rehab instead of one answer at the end. The same record, across your last ten projects, also shows which line items you consistently underestimate, and that is the number that makes the next offer better. It is the same reason to replace the spreadsheets rather than add one more tab to the workbook.
Knowing the number before you sign
If you want to know what a deal made before closing rather than after, the next step is simple. Start the conversation. The first step is a discovery call where we walk through one of your recent projects, from the lead sheet to the closing statement.
Frequently asked questions
Can it handle rentals as well as flips?
Yes. A property you keep as a rental stays in the system with its purchase and rehab history, and later repairs and improvements are logged against it the same way. The record becomes the full cost history of that property in one place.
Does it work with the lender draw process?
The draw request is built from the costs already logged against the project, so the paperwork for the lender is a report rather than a separate assembly job. The numbers you type into the lender portal come from one place.
Do we have to give up the deal analysis spreadsheet we trust?
No. The analysis you run before an offer becomes the first version of the property budget. Your formulas can be built into the record, so the numbers you trusted in the spreadsheet are the ones the project is measured against afterward.
What about the projects already in progress?
Open projects are set up first, with their budgets and the invoices paid so far loaded from your existing workbooks and email. Anything that cannot be matched to a line item is flagged for you to sort out rather than guessed at.
Ready to talk about your project?
Tell us what you're building. Brad reviews every submission personally.
Start Your Project